How to Store, Insure and Sell Gold and Silver — A Stacker's Checklist
Store physical gold and silver where theft, fire and your own mistakes can't wipe it out, insure it for what it's actually worth (a standard home policy usually won't), and keep records good enough to prove it. Ten 1 oz gold coins are worth about $41,609 at today's $4,161/oz spot, so check how your storage, policy and paperwork hold up against that number.
In this guide
- Start With the Number You're Protecting
- Storage Option 1: At Home
- Storage Option 2: A Bank Safe Deposit Box
- Storage Option 3: A Private Depository
- Insurance: Read the Fine Print Before You Need It
- Document Everything (and Keep a Copy Somewhere Else)
- Liquidity: How Fast Can You Turn It Into Cash?
- Common Mistakes
- The Short Checklist
- The Bottom Line
You've bought the coins. Now they're sitting in a sock drawer, and you're not sure if your homeowner's policy would pay a dime if they walked out the door.
Buying is the easy step. Keeping it safe, covered and easy to sell later is where people lose money. This guide covers all three — storage, insurance and liquidity.
This is general information, not legal, tax or insurance advice. Policies, banks and depositories differ, so check your own contract.
Start With the Number You're Protecting
Before picking a safe or a policy, know what the stack is worth today. A guess is not a number.
At $4,161/oz gold and $59.31/oz silver (as of October 13, 2026):
| Holding | Melt value at today's spot |
|---|---|
| One 1 oz gold coin | $4,161 |
| Ten 1 oz gold coins | $41,609 |
| 1 gram of 24K gold | $133.64 |
| A 100 oz silver bar | $5,931 |
| A 500 oz silver monster box | $29,653 |
That's just melt — the floor. It moves every day, so a stack that fit under an insurance limit two years ago may not fit now.
Rule of thumb: re-check your total value every time you add to the stack, and at least once a year.
Storage Option 1: At Home
Home storage is the most common choice. You have instant access, no fees, and nobody else holds your metal.
The trade-off is that you're the security.
What helps:
- A real safe, bolted down. A small safe that two people can carry out is a box with a handle. Bolt it to the floor or a wall.
- Fire rating matters, not just lock rating. Paper receipts and coin flips burn before metal does. A fire-rated safe protects the paperwork.
- Don't keep it all in one spot. Splitting a stack between two hiding places means one bad day doesn't take everything.
- Say less. The biggest home-storage risk is people knowing you have it. Don't talk about your stack, don't post photos with anything that identifies your home, and think twice about deliveries left on the porch.
What hurts:
- Hiding spots so clever that a family member throws them out or sells the furniture they're in.
- No record of what's there. If it's stolen, you'll be trying to remember quantities from memory.
Storage Option 2: A Bank Safe Deposit Box
A safe deposit box gets the metal out of your house and behind a vault door. For a lot of stackers, that's the main appeal.
What surprises people: the contents of a safe deposit box are generally not insured by the bank, and they are not covered by FDIC insurance. FDIC insurance covers deposits — checking, savings, CDs. It does not cover what's in the box. Many box rental agreements also limit what the bank owes you if something goes missing.
Other things to know:
- Access is limited to bank hours. If you want to sell on a Saturday, you can't get to it.
- Some agreements restrict what you can store. Read the rental agreement before you put bullion in it.
- Ask who else can get in if something happens to you. That depends on how the box is titled and on local rules.
If you go this route, you'll likely need your own coverage for the contents. Ask your insurer whether your policy or a rider covers items stored off-premises in a bank box.
Storage Option 3: A Private Depository
Private depositories are vaults built to store precious metals for customers. They usually charge an annual fee, often based on the value or amount stored, and many include insurance as part of the service. Read the terms to see exactly what's covered and for how much.
The words that matter most are how your metal is held:
- Segregated: your exact bars and coins are kept physically separate from everyone else's, often in a labeled bin or box. You get back the same items you put in.
- Allocated: specific items are assigned to you and are legally your property, not the depository's. Depending on the provider, they may sit on shared shelves but are tracked as yours.
- Commingled (pooled / unallocated): your metal is held together with other customers' metal of the same type. When you withdraw, you get equivalent items, not necessarily the ones you deposited.
Segregated usually costs the most, commingled the least. For specific coins you care about — a certain year, a graded slab — commingled storage doesn't make sense.
Questions to ask any depository:
- Is my metal allocated, segregated or pooled?
- Who insures the contents, for how much, and against what?
- How often is the vault audited, and by whom?
- How do I withdraw or sell, and how long does it take?
- What are all the fees — storage, withdrawal, shipping, selling?
Insurance: Read the Fine Print Before You Need It
Most homeowner's and renter's policies treat cash, coins, bullion and precious metals as a special category with a sub-limit for theft — commonly in the low thousands of dollars. Check your policy. Against a stack worth $41,609, a low-thousands limit leaves most of it uncovered.
Common ways stackers get more coverage:
- A scheduled personal property rider (sometimes called a floater or endorsement). You list specific items, often with an appraisal or receipts, and they're covered for a set amount. Ask whether the coverage is for a fixed dollar amount or for market value at the time of the loss — with metal prices moving, that difference matters.
- A separate collectibles or valuables policy. Some insurers write policies just for collections, including coins and bullion.
- Depository insurance. If your metal is in a private vault, coverage may come with the storage fee.
Questions to ask your agent:
- What is my sub-limit for precious metals, coins and bullion, and does it apply to theft only or also to fire?
- Does coverage apply when the metal is stored away from home, like in a bank box?
- What proof would you need if I file a claim?
- Do I need a safe, an alarm or an appraisal for the rider?
Get the answers in writing.
Document Everything (and Keep a Copy Somewhere Else)
Insurance is only as good as your proof. If you can't show what you had, it's your word against an adjuster's.
A good record includes:
- A written inventory: item, quantity, weight, purity, date bought, price paid, seller and where it's stored.
- Receipts: dealer invoices, online order confirmations, private-sale notes.
- Photos: each coin or bar, front and back, with the grade label visible on slabs. A wide shot of the whole stack helps too.
- Serial numbers for bars that have them.
Keep a copy off-site. If the only inventory sits in the same safe as the metal, a fire or burglary takes both. Keep a copy in a cloud account, with a trusted family member or at a separate location.
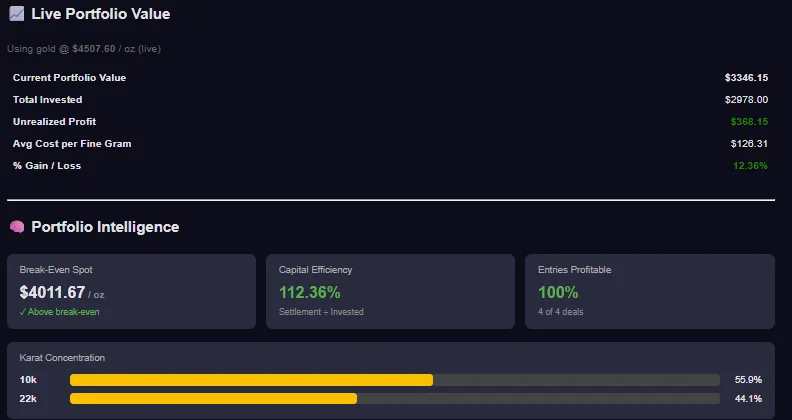
This is also where an app earns its keep. Nu Stack's Holdings keeps each purchase with its weight, purity, photos and what you paid, shows the live value against your cost, and exports the whole list to a CSV or Excel file you can keep off-site. That gives you a current, dated record instead of a spreadsheet you last opened two years ago. (Your cost basis and sale records also matter at tax time — ask a tax professional how they apply to you.)
Liquidity: How Fast Can You Turn It Into Cash?
Liquidity is how quickly you can sell at a fair price.
Bullion vs. numismatics. Recognizable bullion — American Eagles, Canadian Maples, standard bars from well-known refiners — is the easiest to sell. Almost any dealer will buy it and price it off spot. Numismatic and collector coins can be worth much more than melt, but finding the right buyer takes longer, and a dealer may only offer near melt if they don't specialize in that coin.
Buyer channels, roughly fastest to slowest:
- Local coin shop or bullion dealer: often cash or payment the same day for common bullion. Call two shops and ask their buy price before you drive over.
- Online dealers: you lock a price, ship insured, and get paid after they verify — usually days, not hours. Often a better rate on larger lots.
- Private sales (forums, local groups, coin shows): can pay the most, but you handle listing, safety and payment risk, and it takes the longest.
- Pawn shops and cash-for-gold stores: fast, but usually the lowest offers. See where to sell silver and selling precious metal coins for how the channels compare.
Spreads. The spread is the gap between what a dealer sells at and what they buy at. You pay it every time you buy and sell. Example: if a dealer buys a 1 oz gold coin at 2% under spot, you'd get about $4,078 for a coin with a $4,161 melt value. That's an illustration, not a quote — spreads vary by product, dealer and market conditions. Ask for the buy price, not just the sell price, before you buy anything.
Storage affects liquidity too. Metal at home can be sold today. Metal in a bank box waits for bank hours. Metal in a depository may need a withdrawal request, shipping, or a sale through the depository's own process. Know the steps before you need the money.
Common Mistakes
- Assuming the bank insures the box. Generally, it doesn't. Neither does the FDIC.
- Never reading the homeowner's policy. The precious-metals sub-limit is often far below what the stack is worth.
- Keeping the only inventory next to the metal. One fire, two losses.
- Buying hard-to-sell items without knowing it. Odd rounds and obscure coins may carry a premium when you buy and get offered melt when you sell.
- Not updating coverage when prices move. Your stack's value changes with spot, even if you never buy another ounce.
The Short Checklist
- Total up your stack at today's spot.
- Pick storage (home, bank box, depository) and know its trade-offs.
- Read your policy's precious-metals sub-limit — check your policy, don't guess.
- Add a rider or separate policy if the stack is worth more than the limit.
- Build a written inventory with photos and receipts.
- Keep a copy off-site.
- Know your two fastest buyers and their current buy prices.
- Re-check all of the above once a year.
The Bottom Line
Buying metal is only the first step. Store it where one bad day can't take all of it, insure it for what it's worth now, document it like you'll need to prove it, and know who you'd sell to before you need the cash.
For more on building the stack itself, see gold vs. silver investing and the complete melt value guide. To keep a live value on everything you hold, track your stack in Nu Stack.
Frequently asked questions
Is gold in a bank safe deposit box insured?
Generally, no. FDIC insurance covers deposits, not the contents of a safe deposit box, and banks usually don't insure box contents either. If you want coverage, you typically need your own policy or rider. Ask your bank and your insurer to confirm in writing.
Does homeowners insurance cover gold and silver?
Usually only up to a low sub-limit for theft of precious metals, coins or bullion, commonly in the low thousands of dollars. Check your policy. A scheduled personal property rider or a separate policy is the usual way to cover more.
What is the difference between segregated and allocated storage?
Allocated storage means specific bars or coins are held in your name and are your property, not the depository's. Segregated storage goes one step further and keeps your exact items physically separate from everyone else's. Commingled (or pooled) storage holds your metal alongside others' and returns equivalent items, not necessarily the same ones.
What is the fastest way to sell gold or silver bullion?
A local coin shop or bullion dealer usually pays the same day for recognizable bullion like Eagles, Maples and standard bars. Online dealers often pay a little more but take days once you ship. Private sales can pay the most and take the longest.
How should I document my gold and silver holdings?
Keep a written inventory (item, quantity, weight, purity, date bought, price paid, where it's stored), clear photos of each item, and the original receipts. Store a copy somewhere other than where the metal is, so a fire or theft doesn't take the metal and the proof together.
Nu Stack for: Gold Stackers · Silver Stackers · Retirees & Long-Term Holders